How to Evaluate a Financial Advisory Firm
One of the main financial decisions you will make is who you choose to manage or guide your money. Whether you’re planning for retirement, building wealth or just trying to organize your investments, the right advisory relationship can make a real difference – and the wrong one can be costly. If you are looking for the best financial advisor in India, it is good to know what is it that differentiates a credible, well-run advisory firm from one that looks only polished on the outside.
In this guide, we walk through the practical factors to check before you commit credentials, fee structures, transparency, technology, and more and provide a step-by-step due-diligence checklist and questions to ask in your first consultation.
Disclosure: Investing involves risk of loss, including loss of principal. No advisor or platform can guarantee results. This information is to help you better evaluate advisory firms – it is not investment advice. Always assess any firm or product on the basis of your own financial objectives, risk appetite and time horizon.
Why Assessing a Financial Advisory Firm Matters
Financial advice touches almost every major decision you make with your money, how you invest assets, taxes, insurance, retirement and estate planning. Even if nothing obviously wrong happens, a badly regulated firm, opaque on fees or misaligned with your interests can quietly erode your wealth over the years. In contrast, a well-regulated, transparent and competent firm can help you to make better informed decisions and avoid common behavioral mistakes.
As financial advice is a trust-based service, the investor has the main responsibility to check. Which is why you should pick on due diligence and not on marketing statements.
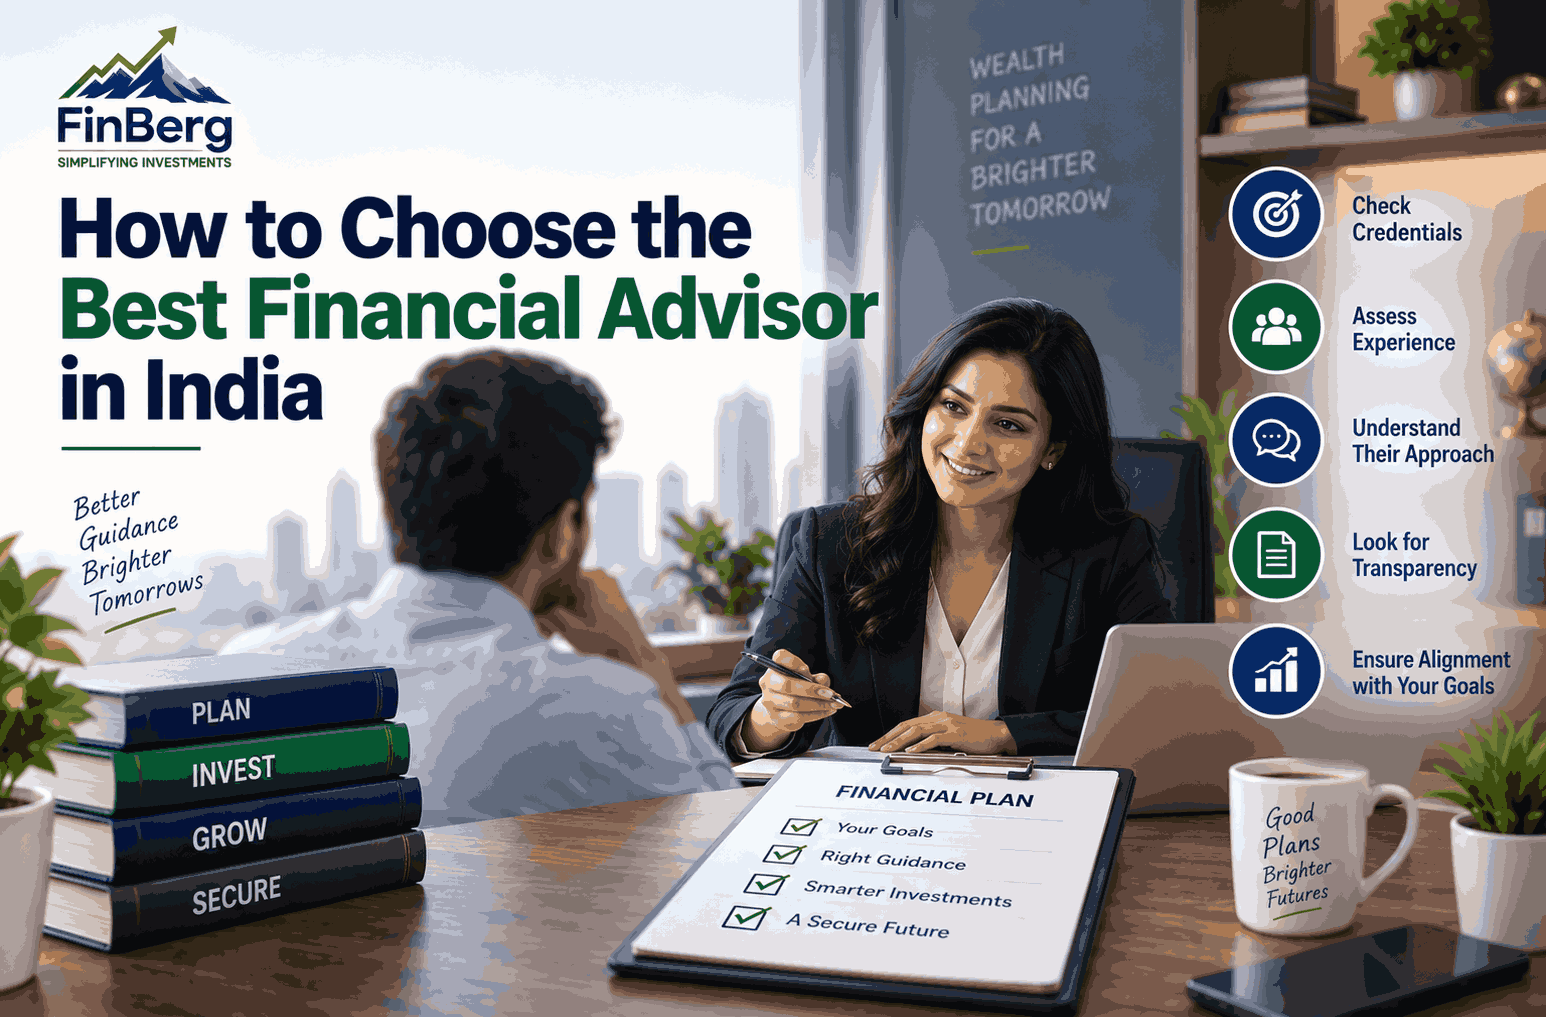
How to Choose the Best Financial Advisor in India
Key Things to Consider When Evaluating a Financial Advisory Firm
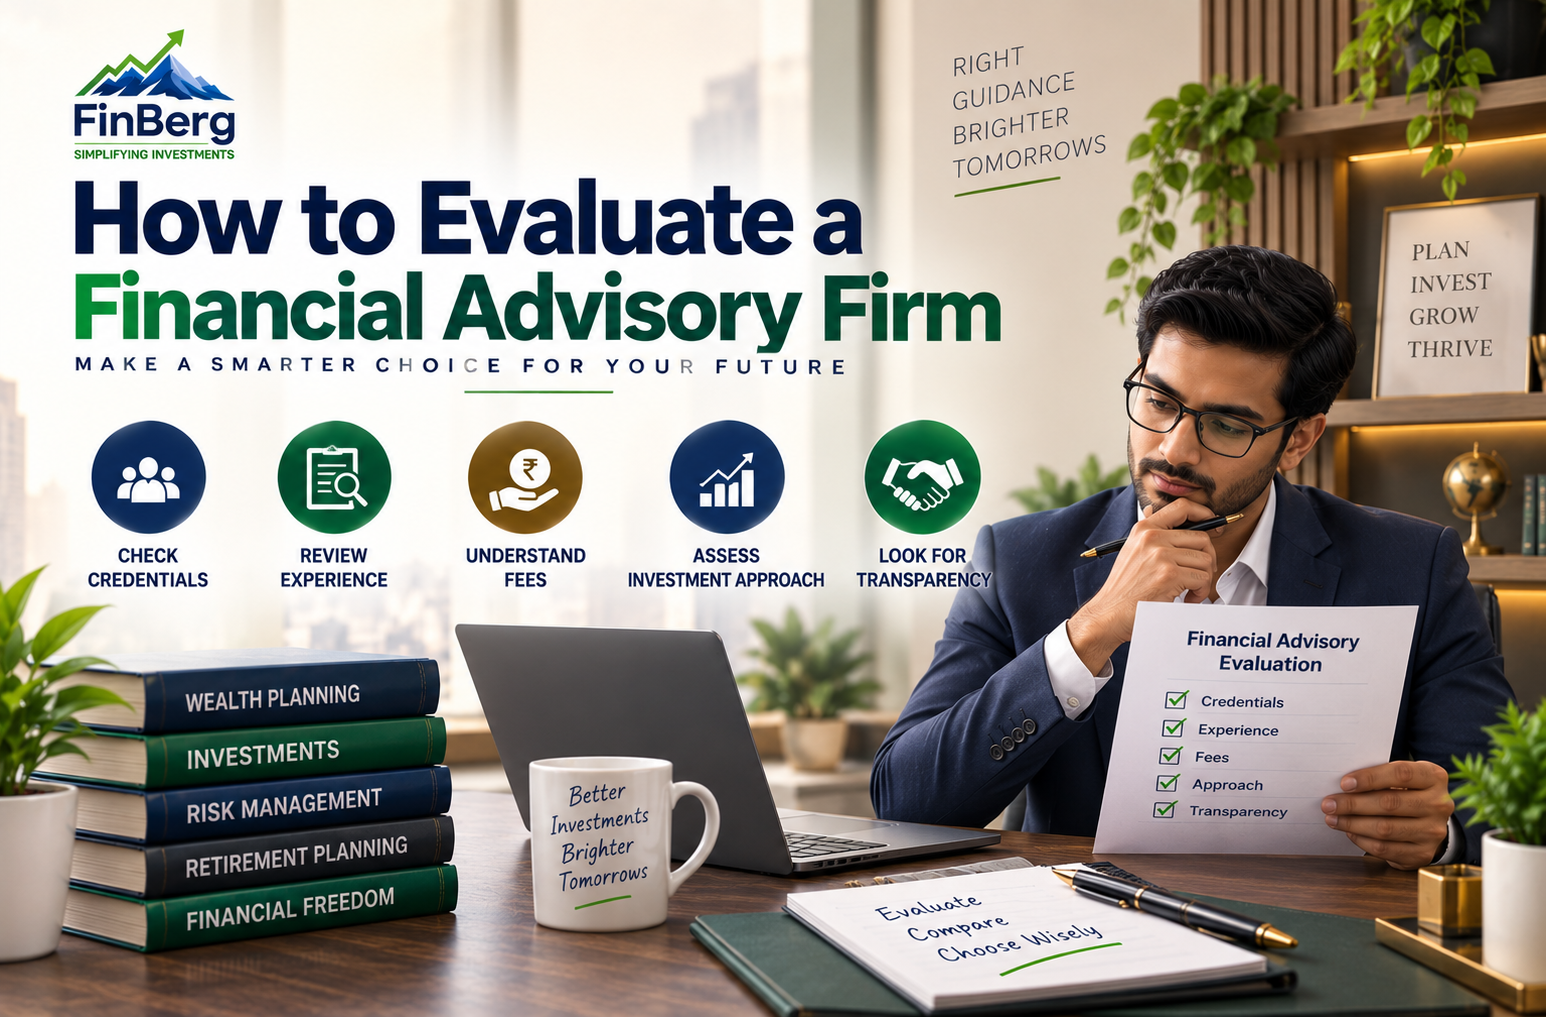
1. Regulatory Registration and Credentials
The first thing to determine in any evaluation is regulatory standing. All entities in India providing investment advice for a fee, are required to be registered as Registered Investment Advisers (RIAs) with the Securities and Exchange Board of India (SEBI) under the SEBI (Investment Advisers) Regulations.
Mutual fund distributors, in contrast, are governed by a different regulatory mechanism (registration with AMFI) and are compensated by way of commissions and not advisory fees and this difference matters in terms of the objectivity of advice received.
But before you go on, check:
If the firm or individual is a SEBI registered Investment Adviser or a distributor
The registration number, and whether it is active and good standing
Any record of regulatory actions, penalties, or complaints from investors against the firm
2. The Advisers' Qualifications and Experience
Don’t just look at the firm brand, look at the people that will be actually advising you:
Relevant qualifications like CFP (Certified Financial Planner), CFA (Chartered Financial Analyst) or NISM certifications required for SEBI registration
Years of experience, and whether that experience fits your particular needs (retirement planning, tax planning, high net worth advisory, etc.)
Whether the advisor is a generalist or has a specialization that is relevant to your situation
3. Investment Process & Philosophy
A credible advisory firm should be able to clearly articulate its investment philosophy:
Does it use goal based planning, asset allocation models or a static set of recommended products?
How does the firm measure your risk tolerance before making any recommendations?
Is this an approach that allows for diversification, time horizon and liquidity needs or does it promote a narrow set of products?
"Be careful of companies that promise returns and not a process. A sound investment strategy is built around your objectives and your tolerance for risk, not around projections of performance.
4. Recommendations visibility
Each interaction must be transparent:
Are the reasons for each recommendation clear, including risks and alternatives considered?
Does the firm disclose any potential conflicts of interest, such as commissions earned on certain products?
Are there any documents (research notes, rationale, risk profiling reports) that you can refer us to, not just verbal assurances?
5. Fee Structure
Knowing how a firm is paid tells you a lot about their incentives. Some common structures in India are –
Fee-only advice - flat fee, hourly rate, or percentage of assets under advice, no product commissions
Compensation for distribution on a commission basis – that is, based on the products sold, which may provide an incentive to sell products with higher commissions.
Hybrid models – a combination of advisory fees and product-related commissions
Ask for the entire fee schedule in writing, including any hidden costs like transaction charges, account maintenance fees or exit loads on recommended products. A reputable company will not be afraid to put this in writing.
6. Services to be Provided
Advisory firms vary greatly in what they actually provide. Indicate if the firm provides:
Comprehensive financial planning (retirement, tax, insurance, estate planning) or investment advice only
Regular evaluation of the portfolio with periodic reviews or one-time consultation
Exposure to a wide range of asset classes (equity, debt, mutual funds, alternative investments) or a limited product range
Match the scope of services to your actual needs - a firm that offers a wide range of services is not automatically the right one if you only need focused, occasional guidance and vise versa.
7. Means of Communication with Clients
How long has this communication been good? Often a good indicator of service reliability:
What is the frequency of portfolio updates or review meetings?
Which channels (face-to-face, telephone, e-mail, chat via app) can I use to ask questions?
What happens when the market’s volatile do they call you, or do you have to call them?
8. Technology & Digital Experience
Today’s advisory firms use technology more than ever for reporting, tracking and communicating. Think about:
If the firm has a secure client portal or app to view holdings, transactions and performance reports
The platform’s data privacy and security stance
Whether online resources really add clarity, or are just a marketing layer over manual processes
9. Risk Management Practices
Ask about the firm’s approach to risk, not just returns:
Does it do a formal risk-profiling exercise before recommending investments?
How does it rebalance if your market conditions or risk profile change?
Does it talk about downside scenarios, worst-case outcomes, not just upside potential?
A company that won’t talk about risk, or does so only in vague terms, deserves closer scrutiny.
Top Mutual Fund Distributors in India: How to Compare Them
How To Vet Claims Made By An Advisory Firm
Marketing material does not constitute evidence. Before you believe any claim check it out yourself:
Registration status – Instead of relying on a certificate shown to you, check the registration of the advisor or the firm on SEBI’s official website.
Disciplinary history – Verify the disciplinary history of regulatory actions, arbitration cases or investor grievances through SEBI’s SCORES (SEBI Complaints Redress System) portal.
Professional certifications – Crosscheck the claimed certifications (CFP, CFA, NISM) with the respective certifying bodies, as these are independently verifiable.
Business Registration – Ensure that the legal entity in which the firm is registered (e.g. with the Ministry of Corporate Affairs, if applicable) is the same as the one presented to you.
References and reviews – Where possible, speak with former clients directly rather than relying only on testimonials the firm has curated.
Typical warning signs to look for
Be wary of an advisory firm that:
Promised or unusually high returns – No legitimate advisor can guarantee the outcome of the market
Urges you to invest quickly or prevents you from taking the time to read documents
Is unwilling to spell out its fee structure in writing
Cannot provide verifiable SEBI registration details
Sells a limited range of products regardless of your goals or risk profile
Exclude risks, disadvantages or conflicts of interest
No documented investment process, relying on informal or verbal recommendations
Discourages you from getting a second opinion or checking out credentials on your own
Due Diligence Checklist – Step By Step
Use this sequence when considering any financial advisory firm:
Check SEBI RIA registration (or AMFI registration in case of distributors) independently.
Check advisor credentials – Verify qualifications and experience to match your needs.
Ask for the fee structure in writing. Find out about all the direct and indirect costs.
Inquire into the investment philosophy – Learn how recommendations are generated and reviewed.
Review sample documentation – Ask to see a sample financial plan, risk-profiling questionnaire or research note format.
Clarify the scope of services – Make sure you know what is included, what is optional, and what will cost extra.
Understand communication cadence – Know how often and in what manner you’ll hear from the firm.
Test the technology available – If there is a client portal or app, give it a go.
Inquire about risk-management processes – Find out how the firm handles rebalancing and downside scenarios.
Look out for red flags – Check against the warning signs listed above.
If you’re unsure, start small – think of it as dipping a toe in the water, rather than diving in headfirst.
Mutual Fund Overlap: How to Check If You Own Too Many Similar Funds
Questions to Ask at Your First Consultation
Are you registered Investment Adviser with SEBI? If yes, please mention the registration number.
What fees, commissions or both do you charge?
What is your investment philosophy and how do you tailor it to each client?
How do you assess my risk tolerance prior to offering recommendations?
What services are included in the deal and what costs extra?
How often will I get updates/reviews and on what channels?
Could you provide a sample financial plan, report format?
What about concerns over potential conflicts of interest?
What if I want to end the advisory relationship?
Pre-IPO Investing Checklist: 10 Things to Verify Before You Invest
Making Smart Choices for Your Financial Journey
There’s no one “best” advisory firm for everyone. It is contingent upon your goals, the complexity of your finances, how involved you want to be, and the kind of ongoing relationship you’re seeking. The most important thing is that the firm is properly regulated and transparent about how it operates and earns and is genuinely aligned with your interests rather than product sales targets.
At Finberg, we believe informed investors make better decisions. Instead of asking who is the best, ask which company has verifiable credentials and transparency that it can prove it is worthy of your trust. Go through the checklist above, ask straight questions, and confirm on your own your financial health is worth your extra effort.
Please note: All investments involve market risk, including the possible loss of principal. No process or philosophy of the past guaranties results in the future. Always remember to check out any advisory firm or investment product in the light of your own financial objectives, risk tolerance and time horizon and seek the advice of a qualified, SEBI-registered investment adviser before making any investment decisions.
Frequently Asked Questions
1. Which factors make a financial advisory firm trustworthy in India?
A reliable company is properly registered with SEBI (or AMFI, in case of distributors), honestly discloses its fee structure, clearly explains its investment approach and puts your goals ahead of product sales.
2. How to check if a financial advisor is SEBI registered?
A genuine SEBI registered Investment Adviser should be able to give their registration number and you can check the registration status of an adviser directly on the official website of SEBI.
3. What is the difference between a fee-only adviser and a commission-based distributor?
A fee-only advisor charges a direct fee for advice and does not earn commissions from products they recommend; that can cut down on potential conflicts of interests. If a distributor is on commission, they are paid for the products they sell, and this is something to keep in mind when judging their recommendations.
4. Is a higher fee always better advisory service?
Not necessarily." Don't just look at fees in isolation as a measure of quality. Compare the fees with the range of services offered and the quality of the advisor, plus the ongoing support you'll get.
5. Can a financial advisory company promise investment returns?
Nope. All investments carry the risk of loss of capital and no advisor or firm can legitimately guarantee returns. Be wary of any firm that says otherwise.
6. How often should I look at my relationship with a financial advisory firm?
Most investors find regular reviews – once a year, say, or whenever you have a major change in your financial objectives, income or life situation – help ensure the advisory relationship still works for them.
7. What documents should I request before hiring an advisory firm?
Before you sign up, ask for the firm’s SEBI registration details, a written fee schedule, a sample risk profiling questionnaire and a sample financial plan or research report format.
Powered by Froala Editor