Financial Advisor vs Wealth Manager: What Is the Difference?
If you’ve begun looking into ways to manage your money better, chances are you’ve seen both words used interchangeably: “financial advisor” and “wealth manager.” But they are not quite the same. Understanding the difference can help you choose the right professional for your financial journey, whether you’re just starting to invest or managing a large, complex portfolio.
This guide explains in detail what each role actually does, who they generally serve, and how to choose one that suits your needs so that when you look for the best financial advisor in India, you know exactly what you’re looking for.
What is a financial adviser?
A fiscal adviser is anybody who helps people make everyday fiscal decisions. They tend to be broad in scope but relatively basic meant to help people build healthy financial habits and work toward specific goals.
Typical Client
Financial advisors generally work with:
Salaried professionals who are just starting out on their investment journey
Young families preparing for education, home loans, or insurance
Individuals seeking retirement or tax planning counsel
Moderate investors who need structured direction
Key Services
Budgeting and Cash Flow Management
Insurance planning (life, health, term cover)
Planning for Retirement (EPF, NPS, mutual funds, PPF)
Investment plans that save tax
Investment planning based on goals (children's education, home purchase, etc.)
Basic mutual fund and SIP advice
How to Choose the Best Financial Advisor in India
Financial Planning Process
The typical financial advisor takes a goal-based, needs-driven approach. They look at your income, expenses, debts and short- to long-term goals, and then suggest a plan to keep you on track usually reviewed annually or when major life events happen.
Investment Management & Portfolio Monitoring
Advisors typically recommend investment products (mutual funds, insurance-linked plans, fixed-income instruments) rather than actively managing a diversified investment portfolio on your behalf. Portfolio reviews are usually periodic, not continuous.
Estate or Succession Planning
That’s usually outside the scope of what a financial advisor is there for. If it’s mentioned at all, it’s usually just generic advice like getting a will or updating nominee details, not full succession planning.
Degree of Personalization
There is personalization, but it is typically standardized around common financial objectives, rather than deeply tailored to complex, multi-generational, or high-net-worth needs.
Top Mutual Fund Distributors in India: How to Compare Them
What Is a Wealth Manager?
A wealth manager provides a more holistic, high-touch approach to managing an individual’s or family’s overall financial life, often combining investments, tax, legal and estate issues into one coordinated strategy.
Typical customers
Wealth managers generally work with:
High net worth individuals (HNIs) and ultra-HNIs
Business owners with complex income streams
Families in need of multi-generational wealth planning
Investors with diversified asset classes (equities, real estate, alternative investments, international assets
Core Services
Investment portfolio management (full service)
Allocation of assets across various asset classes
Tax-efficient investment strategies
Succession and estate planning
Trust creation and legacy planning
Risk management (insurance and alternative investments)
Legal and tax professional coordination
Mutual Fund Overlap: How to Check If You Own Too Many Similar Funds
Financial Planning Approach
Wealth management is typically a comprehensive strategy focused on relationships, that considers investments but also overall net worth, familial dynamics, business interests and long-term legacy goals.
Investment Management & Portfolio Oversight
Unlike basic advisory services, wealth management often includes active, ongoing portfolio management with regular tracking, rebalancing, and adjustments to reflect market movements and changing client objectives.
Considerations of Estate or Succession
This is often a central part of wealth management, including succession planning for family businesses, trust creation and intergenerational wealth transfer strategies.
Degree of Personalization
Wealth management is often very personalized and may include personal relationship managers, tailor-made investment plans, and periodic individual meetings.
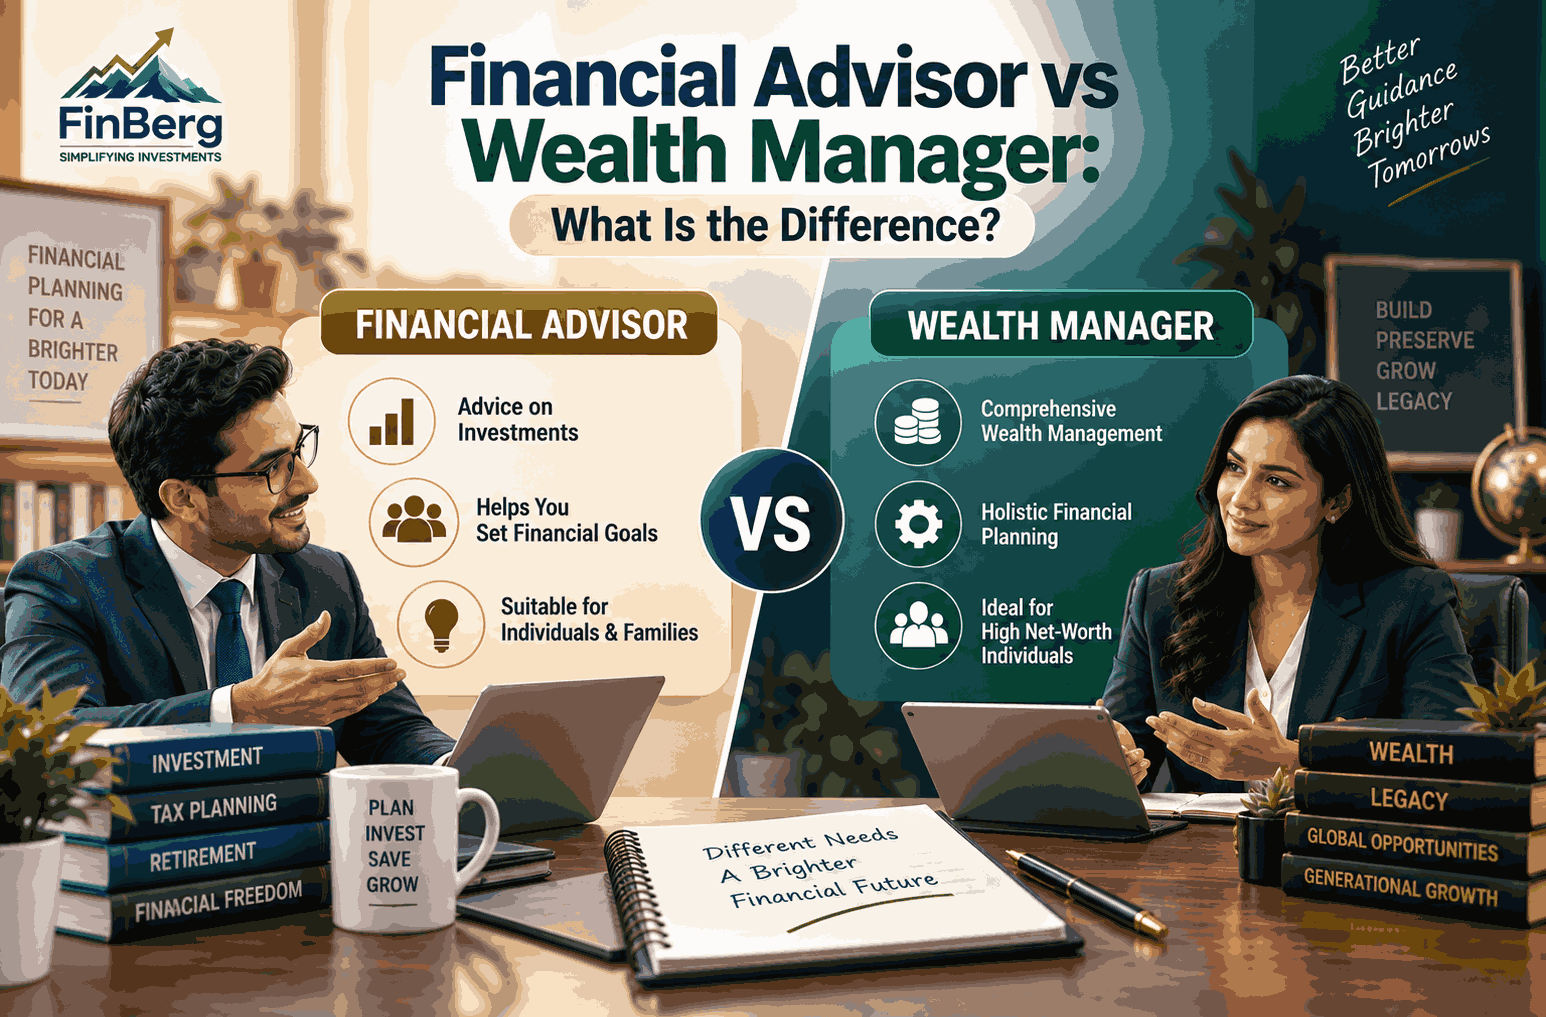
Financial Advisor vs Wealth Manager:
What’s the Difference?
Target Clients: Financial advisors usually cater to individuals, salaried professionals, and young families, whereas wealth managers target HNIs, business owners, and families with complex finances.
Core Services: Financial advisors address budgeting, insurance, retirement and tax planning in addition to goal-based investing. Wealth managers provide investment management, estate planning, tax planning and legacy planning.
Portfolio Management: Financial advisors usually recommend products and do periodic reviews. Wealth managers manage actively and on a continuing basis, rebalancing periodically.
Planning Scope: Financial advisors are concerned with goal-specific planning — retirement, education or tax-saving. Wealth managers look at the big picture including net worth, business interests, succession and legacy.
Estate/Succession Planning: This is rarely included or kept simple with financial advisors, but it is often a core offering with wealth managers.
Personalization: Financial advisory services tend to be standardized and goal-oriented, whereas wealth management is highly personalized and relationship-based.
Ongoing Support: Financial advisors tend to have regular check-ins (annual or semi-annual), while wealth managers offer continuous support, often through a dedicated relationship manager.
Fee Structure: Most financial advisors charge flat fees, hourly rates or commissions. Wealth managers typically charge on an AUM basis (as a percentage of assets under management), charge fixed retainers, or use a hybrid model.
Note: Pricing structures, included services and minimum portfolio sizes vary by provider. Please check details with the business or service provider before you book.
Pre-IPO Investing Checklist: 10 Things to Verify Before You Invest
Financial Advisor or Wealth Manager – When Do You Need One?
You may need a Financial Advisor, if:
You are new to investing and need some help starting out
You are primarily concerned with retirement planning, tax savings, or insurance coverage
You have a moderate investment portfolio and require structured periodic guidance
You have specific goals such as home purchase or educational funding
For instance, a 32-year-old IT professional with a consistent income, looking to initiate SIPs, maximize tax benefits under the old/new regime, and save for a child’s education, would generally benefit from a financial advisor’s structured, goal-oriented advice.
You may need a Wealth Manager if any of the following are true:
You have a sizable and diversified portfolio across asset classes
You own a business and need to plan for succession or exit
You need coordinated tax, legal and estate planning
You want large assets to be actively and continuously managed
Your financial life includes many players (family members, trusts, businesses)
Example: A 50-something business owner with real estate holdings, listed and unlisted equity, and plans to pass on the business to the next generation would likely need a wealth manager to coordinate investment strategy, tax planning and succession structuring.
There isn’t a single “better” choice; it's all about your financial complexity, goals, portfolio size and how hands-on you want a professional to be on an ongoing basis. As your financial situation changes for instance, from accumulating to protecting and passing on wealth your needs may change from simple advice to full-blown wealth management.
Equity vs Debt vs Hybrid Mutual Funds: Which One Should You Choose?
Conclusion
Financial advisors and wealth managers both have an important role to play, but they serve different stages and types of financial journeys. A financial advisor is often the right place to start for individuals working toward specific financial objectives. A wealth manager becomes more relevant as wealth, complexity and legacy considerations grow.
Don’t just select based on titles.
Take a look at your own financial situation goals, portfolio size, level of ongoing support needed and pick a professional or platform that actually matches where you are today and where you’re headed.
FAQs Frequently Asked Questions
1. Is a wealth manager always better than a financial adviser?
Not really. "Better" depends on how financially complex you are and what your goals are. A wealth manager is ideal for someone with significant and diverse assets and estate planning concerns, but many people will be fine with a financial advisor to help with their simple goals.
2. Can my financial advisor become my wealth manager as my portfolio grows?
In some cases, professionals or platforms provide both services, and your relationship may change as your financial needs become more complicated. "Make sure that the provider has a pathway from basic advisory to full wealth management.”
3. What minimum assets do I need to have to work with a wealth manager?
Minimum portfolio or net-worth requirements vary greatly by provider. There is no set industry-wide threshold, so it’s best to check directly with the service provider.
4. Does a financial advisor do tax planning?
Yes, many financial advisors include tax-saving strategies in their services, though this is generally not as comprehensive as the integrated tax planning within wealth management.
5. What are the differences in fees between the two?
Financial advisors are often compensated by flat fees, hourly rates, or commissions, while wealth managers are more likely to use AUM-based (assets under management) fees or retainer models. Actual structures vary by provider. Always clarify costs upfront.
6. Estate planning is for the super-rich?
“No. Wealth managers put more emphasis on estate and succession planning, but basic estate considerations, such as having a will, are relevant to most individuals, regardless of net worth.
7. How to Choose the Best Financial Advisor in India for Your Needs?
Seek out professionals or platforms that have transparent fee structures, relevant certifications such as SEBI-registered investment advisors, a clear planning process, and services that align with your specific financial objectives, rather than generic rankings or claims.
Powered by Froala Editor