Best PMS Companies in India: How to Compare
In India, investors have moved on from mutual funds and are looking for more personalized, concentrated and actively managed portfolios, making Portfolio Management Services (PMS) popular. But, with dozens of PMS providers registered with SEBI, picking the right one is not as easy as picking the one that delivered the best returns last year.This guide demystifies what PMS is, how to evaluate a best PMS company in India for your needs and the red flags every investor needs to look out for before signing on.
What are Portfolio Management Services (PMS)?
Portfolio Management Services are a SEBI regulated investment vehicle where the individual portfolio of securities of the investor is directly managed by a professional portfolio manager and the money is not pooled into a fund structure as in mutual funds. Each PMS client technically owns the underlying shares in their own demat account and the portfolio is customized (at least in theory) to that investor's mandate.
In India, PMS is regulated by SEBI (Portfolio Managers) Regulations and at present there is a minimum investment of ₹50 lakh per client. This makes PMS a product best suited for high net worth individuals (HNIs) and ultra-HNwho prefer more direct ownership, tax-related flexibility and often more concentrated bets than a typical mutual fund would make.
There are typically three types of PMS:
Discretionary PMS – Portfolio manager makes all buy and sell decisions independently within the agreed strategy.
Non-discretionary PMS - the manager recommends, but the investor executes each transaction.
Advisory PMS – Here the manager only advises and the execution is left to the investor.
Portfolio Management Services in Pune for Young Investors: Smart Wealth Planning Tips
Why It’s Harder to Compare PMS Providers Than You’d Think
PMS portfolio is not a standardized one, unlike mutual funds. Portfolios are built over time as money comes in, so two investors in the "same strategy" at the same PMS firm can have meaningfully different holdings and entry points. This makes public return data harder to compare apples to apples and is one reason investors need a broader evaluation framework rather than chasing a single number.
What to Look for When Comparing PMS Companies
1. Regulatory Status and Compliance History
All genuine PMS providers need to be registered with SEBI. First of all:
Cross check SEBI registration number on SEBI website.
Look for any past regulatory actions, penalties or any complaints by investors against the firm.
Verify whether the firm publishes disclosure documents (Form C) as required by SEBI that contain fees, past performance (in the prescribed format) and key risks.
A firm's history with regulators is a better indicator of operational integrity than any marketing brochure.
2. Investment Strategy & Philosophy
PMS strategies vary across large cap centric, multi cap, small and midcap, sectoral/thematic, value oriented or quant driven. Request:
What is the manager’s core investment philosophy and has it held up over market cycles?
Does the strategy align with your personal risk appetite and investment horizon?
Is the strategy easily explained in plain language or is it vague jargon?
A strategy that is clearly articulated and consistently applied is usually a better indicator than one that changes style based on what’s working in the market at the moment.
3. Concentration of portfolio
There is a large concentration risk because PMS portfolios are often more concentrated than mutual funds, sometimes holding only 15-25 stocks, or even less. Typical stock count, weighting of top 5-10 holdings, sector allocation methodology. Higher concentration can multiply gains and losses, so you should be comfortable with this level of risk.
4. Structure for risk management
A credible PMS provider should be able to explain in layman’s terms:
SIZING AND RISK CONTROL TO THE DOWNSIDE.
Do they hedge, use stop-losses or cash allocation in volatile periods.
Not just in bull markets, but how the portfolio did in prior drawdowns (corrections in 2018, 2020, 2022 for example).
Managers who can talk openly about their worst times are normally more trustworthy than those who can only talk of their best performances.
5. Transparency and Disclosure Practices
Look for PMS suppliers who actively share:
Performance reports standardized by SEBI/APMI.
Where applicable, clear disclosure of transactions with related parties.
Honest dialog around changes to strategy, departures of fund managers or changes in AUM.
Avoid companies that are unwilling to give you documentation or that are hesitant to give you detailed disclosures.
6. Pricing Model
PMS fees structures generally have a combination of:
Management fee (usually fixed at 1.5–2.5% p.a.)
Performance fee (typically 10–20% of profits above a hurdle rate).
Exit load on premature redemption.
Some firms offer a pure fixed fee model, some a pure performance fee model, and many a hybrid one. There is no one “right” structure but you should have a precise understanding of how fees compound and how they impact net (not gross) returns.
7. How often and how well do you report?
Good PMS providers will provide investors:
Simple, clear, regular statements about your portfolio (holdings, transactions, valuations).
Performance compared to a relevant index, not a "cherry picked" index.
Real-time visibility through access to a client portal or dashboard.
Bad or late reporting can be a canary in the coal mine.
8. Flexibility and Low Investment
SEBI mandates a minimum of ₹50 lakh, but some PMS providers allow multiple strategies in one account, partial withdrawals or flexibility on fresh capital infusion. Understand lock-in expectations (even if not legally binding) and liquidity management.
9. Communication and Customer Service
Look into the actual accessibility of the fund management team or relationship managers. Do they regularly review their portfolio? Can you get hold of someone who really understands the strategy (not just a relationship manager there to sell you stuff)? This becomes even more critical in volatile markets, when communication is paramount.
10. Track Record – With Context
Track record is important but should be evaluated over several market cycles (preferably 5+ years) not just the last 12-18 months. Always check:
The Ultimate Guide to ETF Investing in India: Types, Strategies & Best Picks
Whether reported returns are net of fees or gross.
Whether the numbers are from a verified, audited source or a SEBI mandated disclosure – not a promotional pitch deck.
How well a product has performed versus a stated benchmark, in both up and down markets.
The portfolios for each client will differ within a single strategy. Any performance number provided should be viewed as indicative and not guaranteed.
Why You Shouldn’t Compare PMS Providers on Short-Term Returns
It's easy to judge PMS companies based on who gave the highest returns in the last year." But this is misleading for several reasons:
A short-term outperformance is often the result of a concentrated bet or a favorable market phase, which may not happen again.
Risk adjusted returns are more important than absolute returns. A strategy that returns 20% with wild swings may be riskier than one that returns 15% consistently.
Survivorship bias and reporting bias are real . Underperforming strategies may be discontinued or merged , biasing the track record that is available .
Fee drag compounds over time, so a headline return figure before fees can look very different net of costs.
A more durable approach is to measure consistency, risk discipline and goal alignment over a full market cycle rather than chasing last year's winner.
Exchange Traded Funds (ETF): Meaning, Benefits, Risks & Smart Investment Strategy
Comparison Checklist for PMS
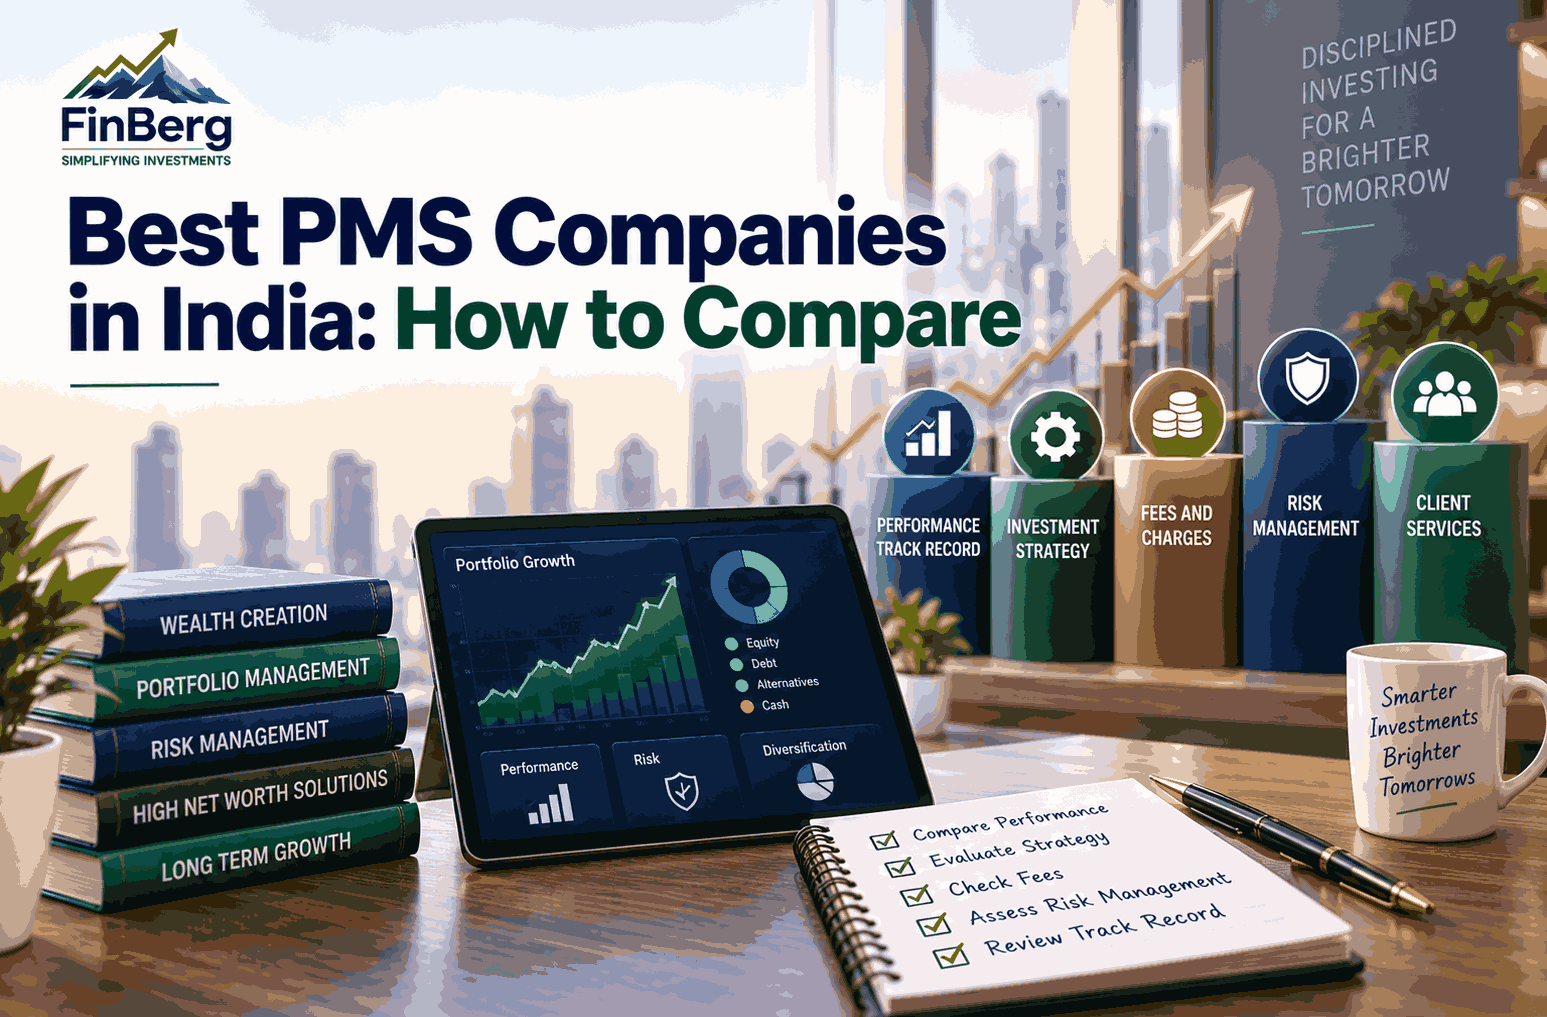
Before selecting a PMS provider, go through this checklist:
Independently verified by SEBI registration
No material regulatory actions or investor complaints
Clear investment philosophy and consistent implementation
Portfolio concentration according to your risk profile
Manager can account for past drawdowns as well as gains.
Transparency of fee structure (fixed + performance + exit load)
Reporting is regular, standardized and benchmarked
Clear minimum investment and liquidity requirements
Access to the real investment team, not just sales, to communicate with
multi-market cycle track record, net of fees
Full review of disclosure documents (Form C)
PMS Investing – Major Risks
Concentration risk – The more you hold of each stock the more volatile it will be.
Illiquidity risk – in stress some underlying stocks, especially small/midcaps, may be harder to exit.
Manager risk – performance is highly reliant on a single fund manager or team. If they leave, it can materially change the strategy.
Fee drag – higher fees than mutual funds can have a meaningful impact on net returns, especially in flat or moderate-return years.
No capital protection – as with all market-linked investments, PMS is subject to full market risk; capital is not guaranteed.
Reporting and Valuation Lag - individual account statements may not always be current with real time market movements.
Considering these risks, PMS is better suited to investors who have a diversified base of core holdings (mutual funds, direct equity, fixed income) and are allocating a part of the surplus capital in higher conviction and higher risk strategies.
How a Mutual Fund Distributor Helps You Choose, Invest, and Stay Consistent Without the Guesswork
Finberg’s Method of PMS Assessment
According to Finberg, selecting a top PMS company in India isn't about a single ranking, but about aligning a provider's regulatory standing, strategy, risk management and fee transparency with an individual investor's goals and risk capacity. “Given the range of portfolios even within the same PMS strategy, investors should do their own due diligence on SEBI disclosures and past performance data rather than rely on marketing claims and treat any comparison as a starting point for deeper due diligence rather than as a final answer.
Stock SIP vs Mutual Fund SIP: Complete Comparison for Indian Investors
Conclusions
There is no single 'best' PMS company in India – the selection depends on your risk appetite, investment horizon, liquidity needs and comfort with concentrated portfolios. When comparing PMS providers, don’t just consider trailing returns, look at the provider holistically regulatory standing, strategy consistency, risk management discipline, fee transparency, quality of reporting and communication. A PMS provider that does reasonably well, but is transparent, disciplined and consistent across market cycles is often a safer long-term partner than one chasing headline returns.
As with any high-ticket investment decision, independent verification is non-negotiable. This can be done via SEBI’s website, Form C disclosures and direct conversations with the portfolio management team. Platforms like Finberg can assist investors in this due diligence process by highlighting the right questions to ask and the right documents to check, rather than pushing a pre-determined “best” choice.
FAQs
1. What is the minimum investment for PMS in India?
SEBI has prescribed a minimum investment of ₹50 lakh for Portfolio Management Services, but some providers may have a higher internal threshold for certain strategies.
2. Are PMS better than mutual funds?
Neither is “better,” per se – PMS has more customization, direct stock ownership and a more focused portfolio, while mutual funds have lower minimums, pooled diversification and a lower cost. The right choice depends on your capital, your risk appetite and your need for personalization.
3. How to check if PMS provider is registered with SEBI?
You can check the registration status of a PMS provider on SEBI’s official website directly. SEBI has listed all portfolio managers with registration numbers.
4. Is the return on PMS guaranteed?
No. Like all market-linked investment products, PMS carries full market risk. The returns are neither fixed nor guaranteed. Nor is past performance any assurance of future results.
5. What do PMS providers typically charge?
Most charge a combination of a fixed management fee (in the region of 1.5-2.5% a year) and a performance fee (usually 10-20% of profits in excess of a hurdle rate), but specifics vary by provider and plan.
6. How are PMS taxed differently from mutual funds?
Since PMS investors directly hold securities in their own demat accounts , capital gains on each transaction are taxed in the investors hands individually , similar to direct equity taxation . In mutual funds , gains are realized only on redemption of fund units . For details see a tax pro.
7. When can I withdraw money from PMS account?
It is contingent upon the individual PMS provider’s terms. However, unlike some other products, PMS generally does not have a strict lock-in period mandated by SEBI, but the service providers might have exit load structures or minimum holding periods that they recommend, which are in line with the investment horizon of the strategy.
Powered by Froala Editor