Mutual Fund Distributor vs Financial Advisor: What Is the Difference?
If you have ever tried to start investing in India, you must have come across two terms that are almost interchangeably used: financial advisor and mutual fund distributor. They sound alike, they both help you invest, they can both point you toward mutual funds but the way they are regulated, what they are paid and what they are actually allowed to do for you are quite different.
This is a difference most investors do not understand as well as they should. It determines what kind of advice you will get, how much you will pay (directly or indirectly) and whose interests are taken into account when a recommendation is made.
Whether you are a first-time investor who wants to explore SIPs or someone looking for the best financial advisor in India to create a long-term financial plan, knowing who you are actually talking to is the first step toward making an informed decision.
This article explains both roles in plain language – what they do, how they’re paid, their regulatory status and how to figure out which one fits your situation. There are platforms like Finberg that exist specifically to help investors navigate this landscape with much more clarity so let’s start from the basics.
Who Is a Mutual Fund Distributor?
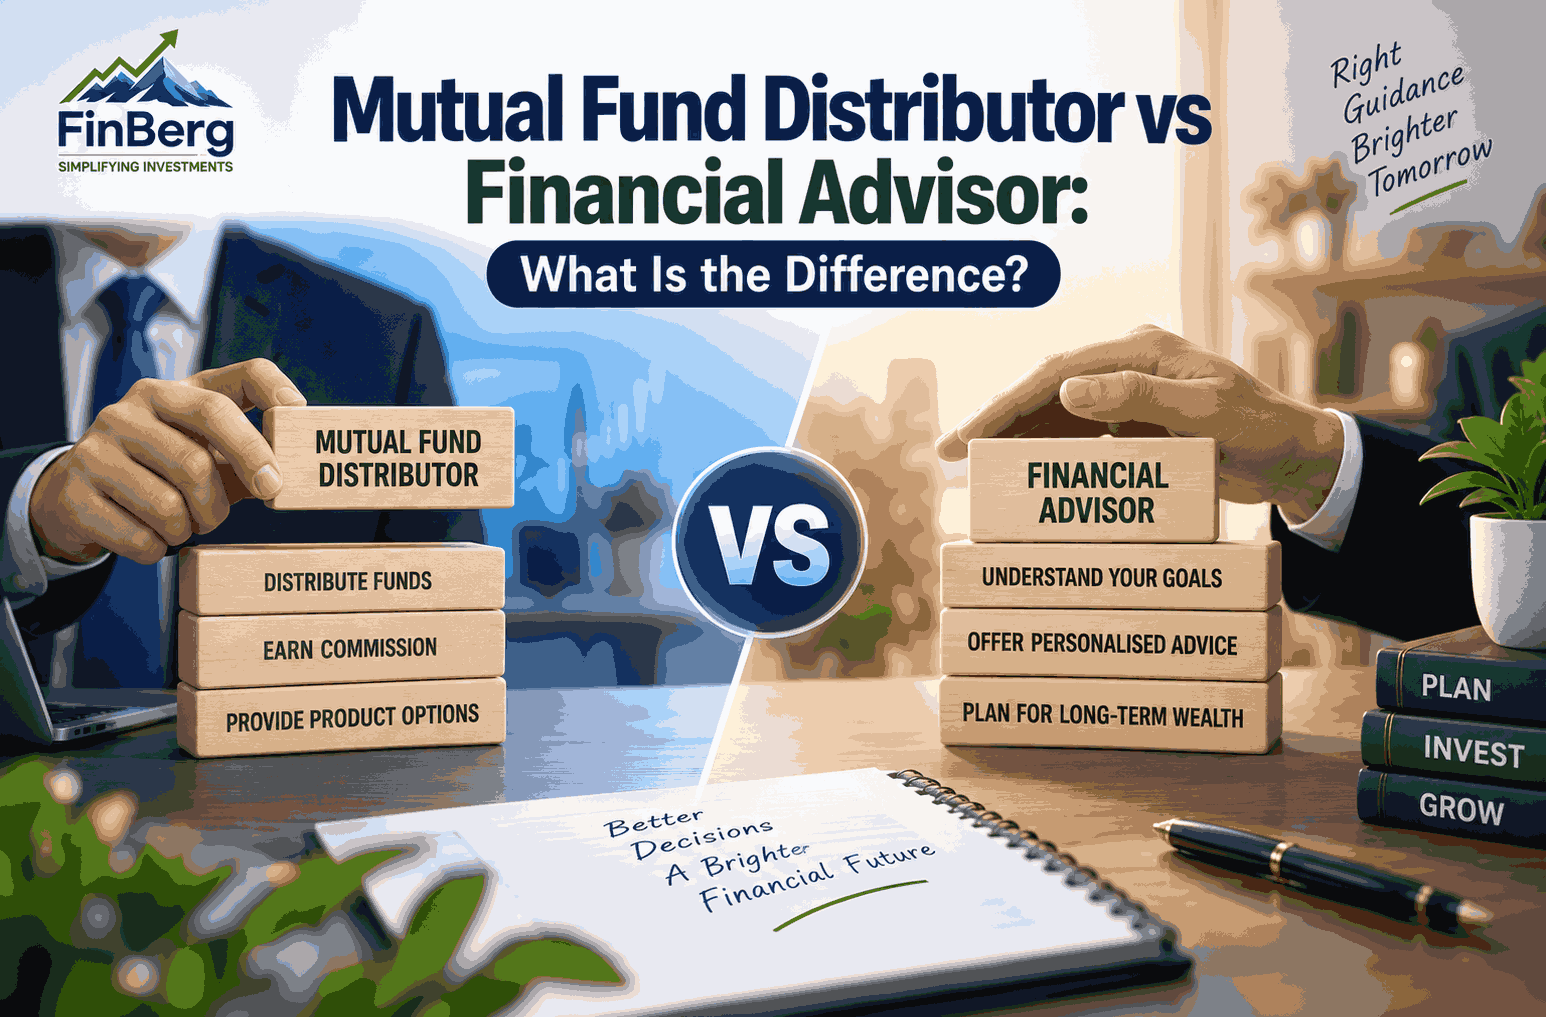
A mutual fund distributor (MFD) is an intermediary registered with Association of Mutual Funds in India (AMFI) and has an ARN (AMFI Registration Number). The main purpose is to help investors select and invest in different mutual fund schemes from different Asset Management Companies (AMC).
What a Distributor Usually Does
Enumerate the different mutual fund schemes available and describe their general characteristics (category, past performance, expense ratio, fund manager, etc.)
Helps in account opening, KYC, transaction processing (purchase, redemption, SIP setup)
Suggests funds according to a general investor profile (risk appetite, goals, time horizon)
Regular performance reports of portfolio
How to Create a Tax-Efficient Investment Strategy Without Compromising Your Financial Goals
What a Distributor Is Not Meant to Do
Distributors are not licensed to provide holistic financial planning such as tax planning, retirement corpus modeling, estate planning, insurance need analysis or a comprehensive investment policy statement across asset classes. As per SEBI and AMFI guidelines, their scope is usually limited to distribution of mutual funds and basic suitability check.
What is a Financial Advisor (Registered Investment Advisor)?
In India, a financial advisor is often called by the name RIA (Registered Investment Advisor). These persons are registered with the Securities and Exchange Board of India (SEBI) under the SEBI (Investment Advisers) Regulations, 2013.
What does a financial advisor usually do?
Gives a detailed review of your financial position, goals, risk appetite, liabilities and existing investments
Develops a comprehensive financial plan that includes mutual funds, equities, insurance, tax efficiency, retirement and estate issues
Provides guidance on all asset classes, not only mutual funds
Discloses and charges a clear fee for advice regardless of what products are ultimately purchased
Is bound by a fiduciary duty, which means they are legally obligated to act in the client’s best interest
RIAs are held to a stricter regulatory standard than distributors, with limits on advisory fees, mandated risk profiling, and limitations on collecting commissions from product manufacturers for the same client relationship.
Top Mutual Fund Distributors in India: How to Compare Them
Mutual Fund Distributor vs Financial Advisor: Key Points of Difference
To define the difference more concretely, let us compare the two roles across all the parameters that matter most to investors:
Regulator: A mutual fund distributor holds an ARN and is registered with AMFI and is regulated by the SEBI’s mutual fund regulations. However, a financial advisor is directly registered with SEBI as Registered Investment Adviser (RIA).
Primary Focus: Distributors’ primary focus is mutual fund sales and transaction processing. Financial advisors offer a full array of financial planning, not just mutual funds.
Investment Selection: Only Mutual fund schemes recommended by Distributor. An RIA can offer advice on mutual funds, stocks, insurance, fixed income and other instruments as part of a broader plan.
Fee/Compensation Model: Typically, distributors receive a trail commission from the AMC, which is incorporated into the expense ratio of "regular plans". Financial advisors charge a flat fee, hourly rate or percentage of assets under management that the client pays directly.
Fiduciary Duty: No requirement that distributors be fiduciaries. RIAs are required by regulation to act in their client’s best interest.
Depth of Financial Planning A distributor’s role is generally restricted to the basic suitability assessment for mutual fund products. Typically, an advisor will create a comprehensive financial plan that includes retirement planning, tax efficiency, goal setting, insurance needs and estate planning.
Ongoing Support: Typically distributors provide portfolio updates and transaction support. Advisors often provide ongoing plan reviews, rebalancing advice and tracking progress toward goals over time.
Conflict of Interest: As the income of a distributor may be different for different fund or AMC, there is a higher possibility of conflict of interest. The fee-only model of an advisor is set up to minimize this, as the compensation is not connected to the sale of any particular product.
Cost to Investor: The cost to the investor when using a distributor is indirect and hidden in the expense ratio of regular plans. With an advisor, the cost is direct and stated up front as an advisory fee.
Best For: Distributors are often a good fit for investors who want simple, transaction-based mutual fund investing. If you’re after structured, goal based, multi-asset financial planning, then advisors are better suited.
Mutual Fund Overlap: How to Check If You Own Too Many Similar Funds
Compensation Models Explained
This is where you’ll see the difference in your pocket most clearly.
For mutual fund distributors, they usually earn from trail commissions paid by AMCs, which are included in the expense ratio of “regular plans”. You are not paying the distributor directly from your pocket – the cost is embedded in the ongoing charges of the fund which slightly reduces your returns over time as compared to a “direct plan” of the same scheme.
In contrast, you pay financial advisors, or RIAs, directly, whether it's a flat fee, an hourly rate, or a percentage of assets under advisory. To help mitigate conflicts of interest, SEBI regulations prohibit RIAs from earning distribution commissions on the same client relationship at the same time.
Neither model is inherently “wrong” but the incentive structure can affect what is recommended, and that’s why it’s important to understand it.
Conflict-of-Interest Considerations
A distributor’s income depends on which schemes an investor buys. Hence there is a natural (even if unintentional) incentive to lean toward funds or AMCs that offer relatively higher trail commissions. That doesn’t mean all recommendations are compromised, but structurally it’s possible.
This is one of the conflicts that the fee-only structure of an RIA is designed to mitigate, as their compensation is independent of your choice of fund or AMC. But RIAs aren’t without conflict, either. For example, AUM-based fees may provide an incentive to keep more assets under management, rather than recommending the client pay off debt or spend to achieve a goal.
All investments carry market risk and no advisor, regardless of model, can guarantee returns. Any professional or platform that promises guarantee or fixed returns from market linked instruments should be dealt with caution as this is against SEBI’s investor protection norms.
Pre-IPO Investing Checklist: 10 Things to Verify Before You Invest
Who Should Consider a Mutual Fund Distributor?
Investors who are newish to investing and want guided help with simple mutual fund transactions
Those with simple goals (e.g. SIP investing) and do not require multi-asset or tax planning advice
Investors willing to pay the cost in the expense ratio, rather than separate fee
People who like face-to-face, relationship-based hand-holding for their daily transactions
Who Should Use a Financial Advisor (RIA)?
Investors with more complex financial situations multiple income streams, existing debt, tax planning needs, or who are nearing retirement
People who want a documented financial plan based on their goals, not on products
Investors who want to reduce the potential for conflicts of interest and prefer transparent, fee-based pricing
People who want ongoing plan reviews rather than just transaction support
There’s no one-size-fits-all answer. The right choice depends on how complex your finances are, your comfort level with fees, and how much planning (versus product execution) you really need. Many Indian investors also use a hybrid method, using a distributor for simple transactions and consulting an RIA for broader planning on a periodic basis.
Questions to Ask Before Choosing
Before you approach a distributor or advisor, ask yourself:
Who are you registered with? Are you? (For distributors, request the ARN number and for advisors, the SEBI RIA registration number.)
How do you get paid for the advice or products you recommend?
Are you just selling on behalf of someone else or do you have a fiduciary duty to me?
How much will I end up paying – direct and indirect costs – over the next 5 to 10 years?
Can you tell me about your recommendation process, not just the ultimate suggestion?
Are you providing planning across all asset classes or just mutual funds?
How often will you review my portfolio or financial plan?
Asking these questions and comparing the answers is one of the best ways to assess whether a given distributor or advisor is right for you, rather than relying on marketing claims alone.
Equity vs Debt vs Hybrid Mutual Funds: Which One Should You Choose?
A Note on Regulatory Safeguards in India
India has considerably tightened its regulatory framework for both distributors and advisors in the last few years. SEBI has made it mandatory for RIA to do risk profiling, suitability assessment and disclose fees clearly. AMFI has made it mandatory for distributors to disclose their ARN commission structure on request.
Investors must verify credentials from the official SEBI and AMFI registers before hiring any professional. They must be wary of any professional who is hesitant to share his registration status and compensation model.
Also, please remember that mutual fund investments are subject to market risks and past performance of any scheme is not indicative of the future returns. Please read all the scheme related documents carefully and consult your own financial adviser regarding your specific financial situation before making any investment decisions.
Conclusion
The question of a mutual fund distributor versus a financial advisor is not which is better, but which model is best for your financial complexity, planning needs and comfort with different fee structures. A distributor might be better for simple mutual fund investing, while an RIA is usually better for investors who can benefit from comprehensive financial planning with fiduciary backing.
At Finberg, our goal is to help Indian investors understand these differences clearly, so that whether you are looking for the best financial advisor in India or just trying to begin with your first SIP, you are doing so with full understanding of the roles, cost and regulatory protections involved. Explore Finberg’s resources to compare your choices and make a better choice for your financial journey.
Frequently Asked Questions
1. Are mutual fund distributors and financial advisors the same?
No, a mutual fund distributor is a person who is registered with AMFI and deals mainly in mutual fund transactions. SEBI registered RIA offers complete fee based financial planning across asset classes.
2. Do I pay the mutual fund distributor directly?
Usually not. In the case of “regular plans” commissions paid to distributors are normally included in the expense ratio. The cost is therefore indirect, and eats away at your returns over time, rather than being charged to you separately.
3. Do financial advisors cost more than mutual fund distributors?
It comes down to what you want to invest and what you need. RIAs charge a direct disclosed fee. That fee may seem higher at first glance, but it can be more transparent and, in the case of complex financial situations, potentially cheaper over the long run than paying embedded commissions.
4. Can a mutual fund distributor also be a financial advisor?
Some professionals are registered as RIA and ARN at the same time but SEBI regulations generally require them to keep the two roles separate and the compensation structures separate for the same client to avoid conflicts of interest.
5. How can I tell if an investment advisor is registered with SEBI?
The professional's SEBI RIA registration number is publicly available and can be checked on the list of registered investment advisers on the SEBI website or directly asked by the professional.
6. Is it just a matter of picking the “best financial advisor in India”?
There is not one “best” advisor for everyone; it is contingent upon your financial objectives, complexity, risk profile, and the advisor’s registration, fee structure and track record of transparent conduct. Don’t concentrate on the rankings, but rather on a few alternatives that suit your particular requirements.
7. Do I run a risk in investing in mutual funds, regardless of who advises me?
Yes. All investments in Mutual Funds are subject to market risk and neither any distributor nor advisor can assure or guarantee returns. Please read the scheme related documents carefully before investing.
Powered by Froala Editor