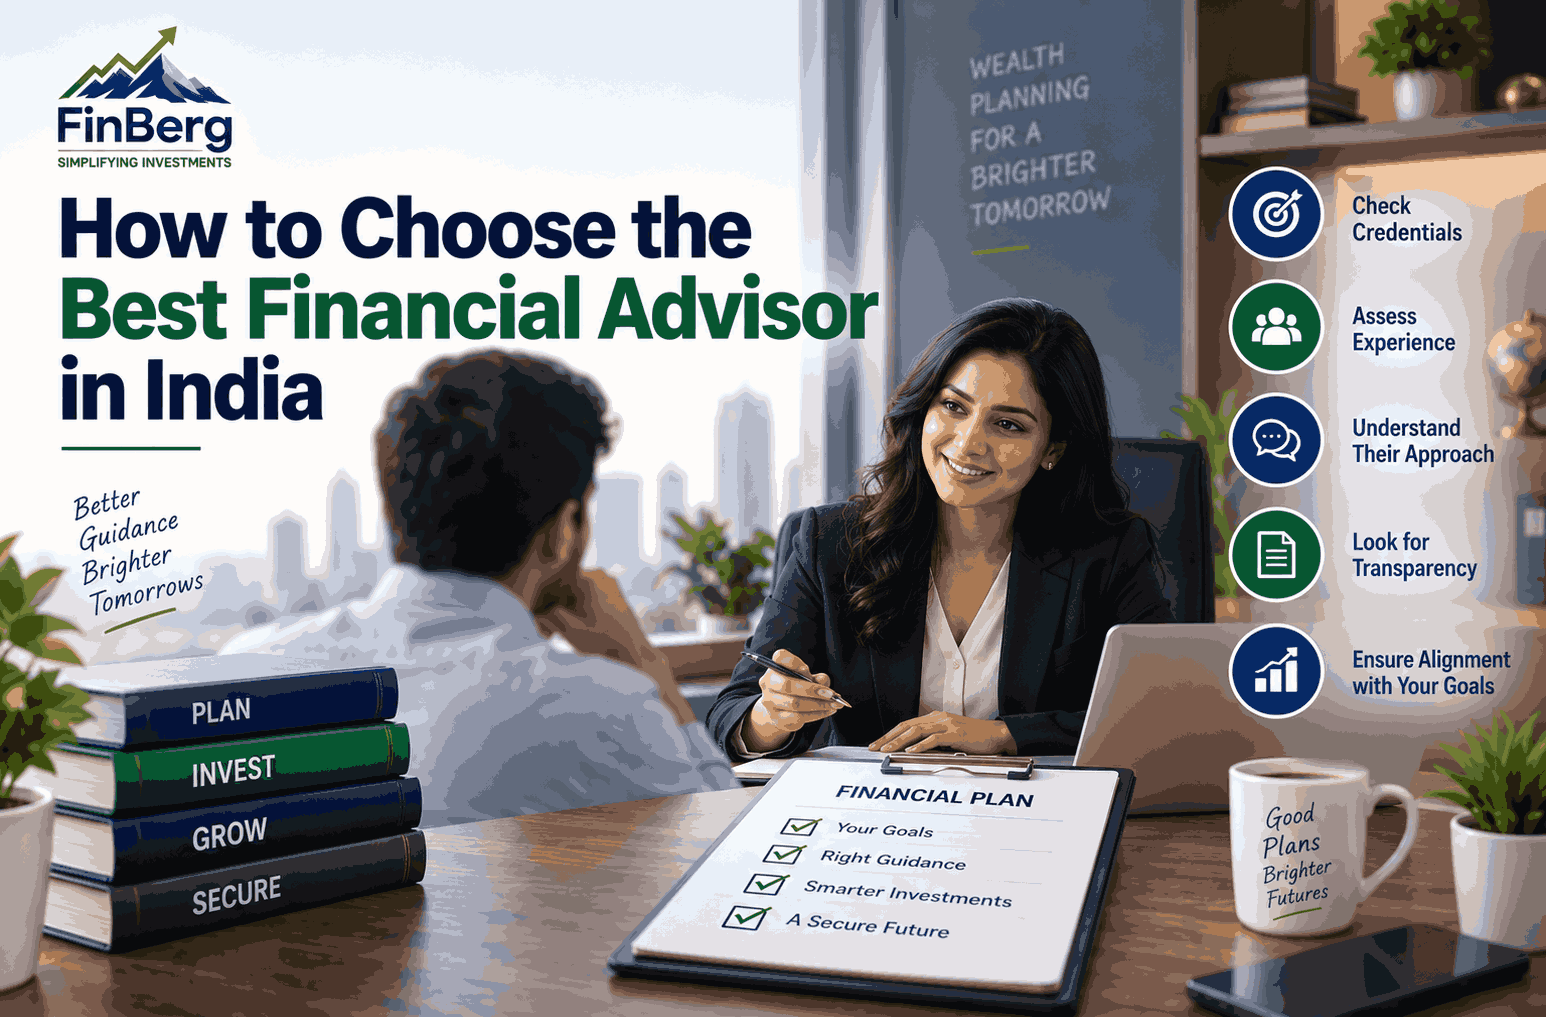
How to Choose the Best Financial Advisor in India
One of the most important financial decisions you’ll make is choosing the right person to help you make money decisions. With thousands of professionals in India claiming to be “advisors”, “planners”, “wealth managers” or “distributors”, it’s easy to get confused about who really has your best interests in mind.
This guide tells you exactly what to look for so you can find the best financial advisor in India for your specific situation and not just someone with a polished pitch.
Why Choosing the Right Financial Advisor Matters
A good advisor doesn’t just sell products they help you put a financial plan in place that corresponds to your goals, risk appetite and life stage. Poor fit could mean investments that don’t match, fees you don’t need to pay or commissions being the driver of the advice you’re given, not your needs. The effects compound over years, so it’s worth investing real time in this decision, rather than taking the first person who knocks on your door.
How to Create a Tax-Efficient Investment Strategy Without Compromising Your Financial Goals
Understand the Different Types of Financial Professionals in India
It’s helpful to know what each title means before you start judging anyone. These terms are often used broadly but apply to different services with different regulations.
Money Management
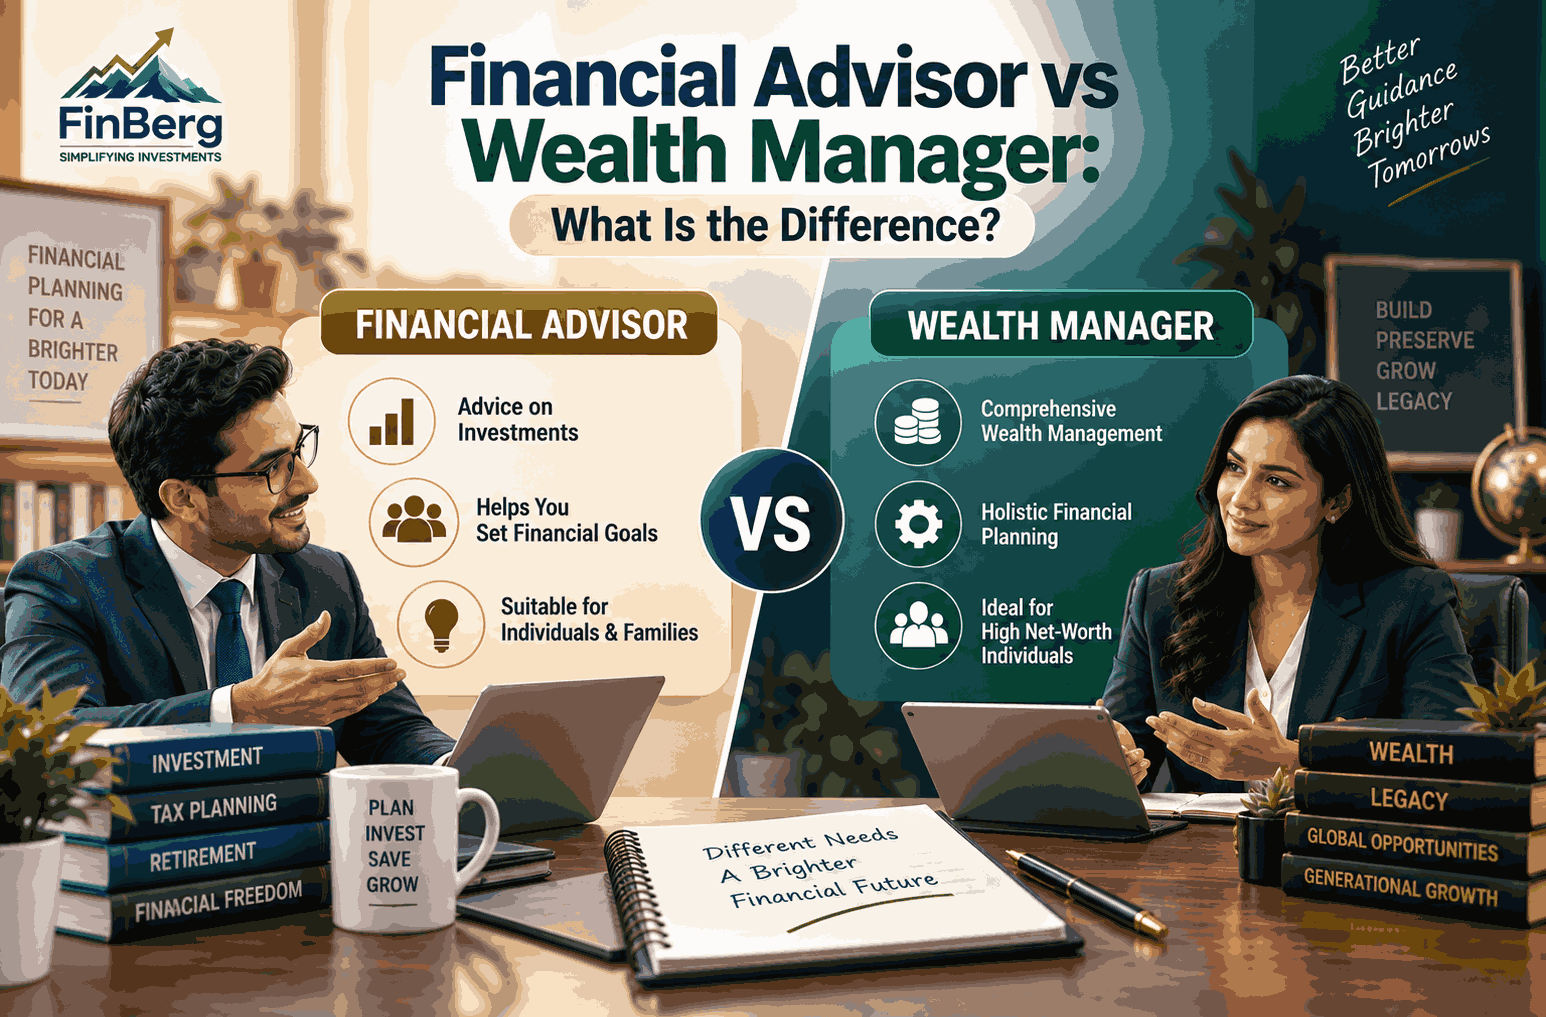
A financial planner looks at all of your financial information income, expenses, debts, insurance, taxes, retirement, and goals and creates a plan to help you get from where you are to where you want to be. Planning is broader than investing alone and may or may not include specific product recommendations.
Financial Advice
This is specific advice on where to put your money: which asset classes, funds or securities are right for your goals and risk profile. In India, the professionals who provide personalized investment advice charging a fee are required to be registered with SEBI as Registered Investment Advisers (RIAs). RIAs are under a fiduciary-style obligation to act in the client’s interest.
Distribution of Mutual Funds
Mutual fund distributors (MFDs, brief) help investors to choose and invest in mutual fund schemes. They are usually paid a commission (built into the expense ratio) by the fund house and do not charge any fee directly from the investor. Distributors are registered with AMFI and not with SEBI and they cannot charge advisory fees for giving personalized advice.
Wealth Management
Wealth management is a more holistic, often relationship-based service typically targeted to high-net-worth individuals. It may blend investment management, tax planning, estate planning and sometimes banking or lending services, provided by a dedicated relationship manager or team.
First, you need to know which of these you actually need. Someone looking for one-time retirement planning has very different needs than someone looking for ongoing portfolio management.
Top Mutual Fund Distributors in India: How to Compare Them
Key Factors to Evaluate When Choosing a Financial
Advisor
1. Credentials and Qualifications
Look for recognized qualifications such as CFP (Certified Financial Planner), CFA (Chartered Financial Analyst) or relevant post graduate degrees in finance or commerce. Credentials don’t mean everything. But they do represent a minimum level of organized knowledge, and a continuing commitment to standards of professionalism.
2. Status in the Law
In case the advisor charges a fee for giving customized investment advice, then check whether he is registered with SEBI as an RIA. Check their registration with AMFI as a distributor if they are earning commissions. You can check SEBI RIA registration on the official SEBI website. That one check says a lot about how they pay you and what obligations they have to you.
3. Experience and Past Record
Ask them about their experience, the type of clients they usually deal with and whether they have handled cases similar to yours (retirement planning, NRI investments, business owners etc). Watch out for any one who guaranties returns. No legitimate advisor can guarantee investment performance and past performance of any scheme or strategy does not guarantee future results.
4. Investment philosophy
Every advisor has a philosophy, some are passive, low cost investors and others are more active and research driven. Ask them to explain their philosophy in layman’s terms, and see if it matches your level of comfort with risk and market volatility.
5. Expenses
Advisors may charge a flat fee, hourly fee, percentage of assets under management (AUM), or commission based on products they sell. Understand exactly how they are paid because it impacts the advice you get. In general, a fee-only advisor (no commissions) has fewer inherent conflicts of interest than one that earns commissions for the products they sell.
6. Conflits d'intérêts et transparence
Ask them directly if they get any type of commission, referral fee or incentive that is attached to certain products. And a good advisor will tell you that and not duck the question.
7. Communication mode and availability
Are you having quarterly reviews, annual check-ins or just calling for advice? Do they say what they mean, or do they drown you in jargon? Good advisors communicate at your level of understanding of finance and keep you informed without overwhelming you with information.
8. Services to be Provided
Some advisors sell only mutual funds. Others sell insurance, tax planning, estate planning, retirement and more. Match scope of services to what you actually need No point paying for full-blown wealth management if you just need some help picking out a few mutual funds.
9. Alignment with your financial objectives
Maybe the most important test: Does the approach they suggest truly fit your goals, time horizon, income stability and risk tolerance or does it sound like a cookie-cutter sales pitch they give to everyone?
Mutual Fund Overlap: How to Check If You Own Too Many Similar Funds
Financial Planning vs Investment Advice vs Mutual Fund Distribution vs Wealth Management
Financial planning encompasses all of your financial life goals, insurance, tax and retirement. They are usually fee-based and are best for those looking for a full roadmap, not just investment picks.
Investment advice means advice on investment recommendations. In India, professionals offering this for a fee are meant to be SEBI-registered (RIA) and generally have a fiduciary-style duty, so it’s a good fit for investors who seek unbiased, personalized guidance.
Mutual fund distribution is assisting investors with selecting and implementing mutual fund investments. Distributors are registered with AMFI and are paid through commissions embedded in the fund’s expense ratio, instead of a direct advisory fee this suits investors mainly looking for help executing mutual fund investments.
Wealth management is a broader, relationship-driven service typically targeted at high-net-worth individuals with complex needs. It can be fee-based, AUM-based, or some combination and may bundle investments, tax and estate planning together.
Pre-IPO Investing Checklist: 10 Things to Verify Before You Invest
Practical Checklist Before Hiring a Financial Advisor
Use this checklist for your first meeting or consultation:
Is the advisor registered with SEBI (RIA) or AMFI (distributor) Have you checked this yourself?
What are their qualifications and how many years of experience do they have in the field?
Exactly how are they compensated fee, commission, or both?
Do they at the beginning clarify any possible conflicts of interest?
What is their process for assessing your risk tolerance and financial objectives?
Will they write down your risk profile and financial plan?
How often will your portfolio be reviewed and in what format (call, report, meeting)?
Can they give us references or client testimonials (without breaching confidentiality)?
What if you want to leave the relationship – are there lock-ins or exit costs?
Do they offer a written agreement that clearly spells out services and fees?
Do they not promise guarantyd or specific returns?
Do they tell you their investment philosophy in a way you truly understand?
Common Mistakes to Avoid When Choosing a Financial Advisor in India
Chasing past performance.
Past performance of that fund or advisor is no guarantee of repeating that performance. Markets move in cycles and chasing recent winners is often bad timing.
Disregarding the fee structure.
Small percentage fees or commissions can add up to big numbers over decades. “Always know the long-term cost, not just the headline number.
No regulatory registration check.
Most investors don’t check SEBI or AMFI registration and become victims of unregistered or unqualified persons acting as advisors.
Confusing a salesperson with an adviser.
Some people are in the business of selling a product (e.g. insurance-linked investment plans) and not in the business of giving holistic advice. Ask pointed questions to differentiate.
Bypassing the risk assessment step.
If your advisor recommends investments without first understanding your risk tolerance, time horizon and goals that’s a red flag.
Not putting things down on paper.
Verbal promises are hard to hold anyone to. Ask for written financial plans, risk profiles and fee agreements.
Believing in promises of guarantyd returns.
No real advisor can promise market-linked returns. Such claims are a serious warning sign.
Ignoring reviews in progress.
A financial plan is not a one-time event. Your goals, income and market conditions change. Review your plan periodically.
Equity vs Debt vs Hybrid Mutual Funds: Which One Should You Choose?
Conclusion
There is no one “best financial advisor” for all investors. The right one depends on your goals, how complicated your finances are and how comfortable you are with different fee structures. Asking an advisor about regulatory registration, how they get paid, conflicts of interest, and requiring documented, goal-based advice will put you in a great position to make a confident, informed decision. Ask direct questions, take your time and remember that a good advisor will appreciate your due diligence and not rush you through it.
Frequently Asked Questions
1. How to verify whether a financial advisor is SEBI registered?
You can verify the status of the advisor by searching the list of Registered Investment Advisers available on the SEBI website by name or registration number.
2. SEBI RIA vs mutual fund distributor difference?
An RIA is registered with SEBI and is supposed to give personalized investment advice for a fee and typically has a fiduciary kind of duty to the client. A mutual fund distributor is registered with AMFI and earns commissions from fund houses and not direct advisory fees.
3. How much does it cost to hire a financial advisor in India?
Fees vary widely – flat fees, hourly rates, retainer models or a percentage of assets under management are all typical. There is no set “standard” rate so it’s important to compare structures not just the amount.
4. Can a financial advisor promise returns on investments?
No. Market linked investments are risky and any advisor promising guarantyd or fixed high returns should be treated with caution.
5. Do I need a financial advisor if I am investing only in mutual funds through SIPs?
It is contingent upon how comfortable you are. Many investors do their simple SIP-based investing themselves, while others prefer professional advice for goal-based planning, tax efficiency and periodic portfolio reviews.
6. How frequently should I review my financial plan with my advisor?
Most advisors recommend at least an annual review, with periodic check-ins after big life events (job change, marriage, buying a house) or big market moves.
7. What paperwork should I be getting from a good financial advisor?
Request a written engagement/fee agreement, a documented risk profile assessment, and a clear investment or financial plan versus just verbal recommendations.
Powered by Froala Editor